FFM Fund Newsletter - Sep 2026
September 2026
Dear Friends, Dear Investors,
It sometimes feels as if we are repeating ourselves, but everything continues to hinge on the same AI dynamic, with its ups and downs and capital expenditures that defy comprehension.
The latest illustration is the imminent stock market listing of Anthropic, the company behind Claude, at a valuation of around USD 80 billion. To put that figure into context, this year alone Alphabet raised USD 80 billion in its first equity issuance since its 2004 IPO, SpaceX USD 85 billion, and Anthropic is set to do the same. We are living in a world where companies that did not exist twenty years ago are raising in a matter of weeks amounts that would have been sufficient to finance a decade of post-war European reconstruction.
Even in the age of trillion-dollar market capitalisations, these are substantial sums and not easily found. This phenomenon has a direct and little-remarked consequence. For the first time since 2008, equity issuances now exceed buybacks. Yet few signals are as legible in markets. When companies buy back their own shares, they are telling you they believe them to be cheap.
When they issue shares, the message is the reverse. The world's largest companies are sending an unambiguous signal right now. The only comparable exception remains 2008, when banks had to issue record amounts of stock in order to survive, which is not exactly a reassuring precedent.
Meanwhile, our investments in old economy stocks, energy and materials above all, are starting to truly bear fruit. This comes as little surprise to those who know the history of US markets. Since oil was discovered in the hills of Pennsylvania in 1859, the US stock market has oscillated between two great poles of attraction, energy and technology. Everything else is almost beside the point. The great cycles alternate between the two, each taking over from the other at the very moment no one expects it any longer. The long technological dominance of the 2010s and 2020s is gradually giving way to a return to favour of the traditional capital-intensive sectors, exactly as was the case between 2000 and 2008..
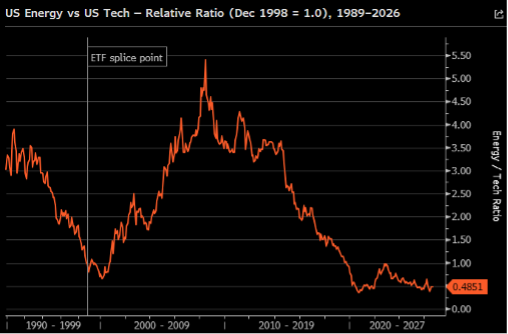
We believe we are in a new transition phase for which the majority of market participants are not prepared. Large institutional allocations remain heavily skewed towards technology and AI, while energy and materials remain underrepresented in portfolios. This positioning has not yet fully corrected, and that is precisely where the opportunity lies.
Best regards,
Your CaridaB Group Team


Comments